All Categories
Featured
Integrating Life Insurance with Special Needs Trust Planning
Table of Contents
, so lots of individuals presume that they do not qualify for protection.
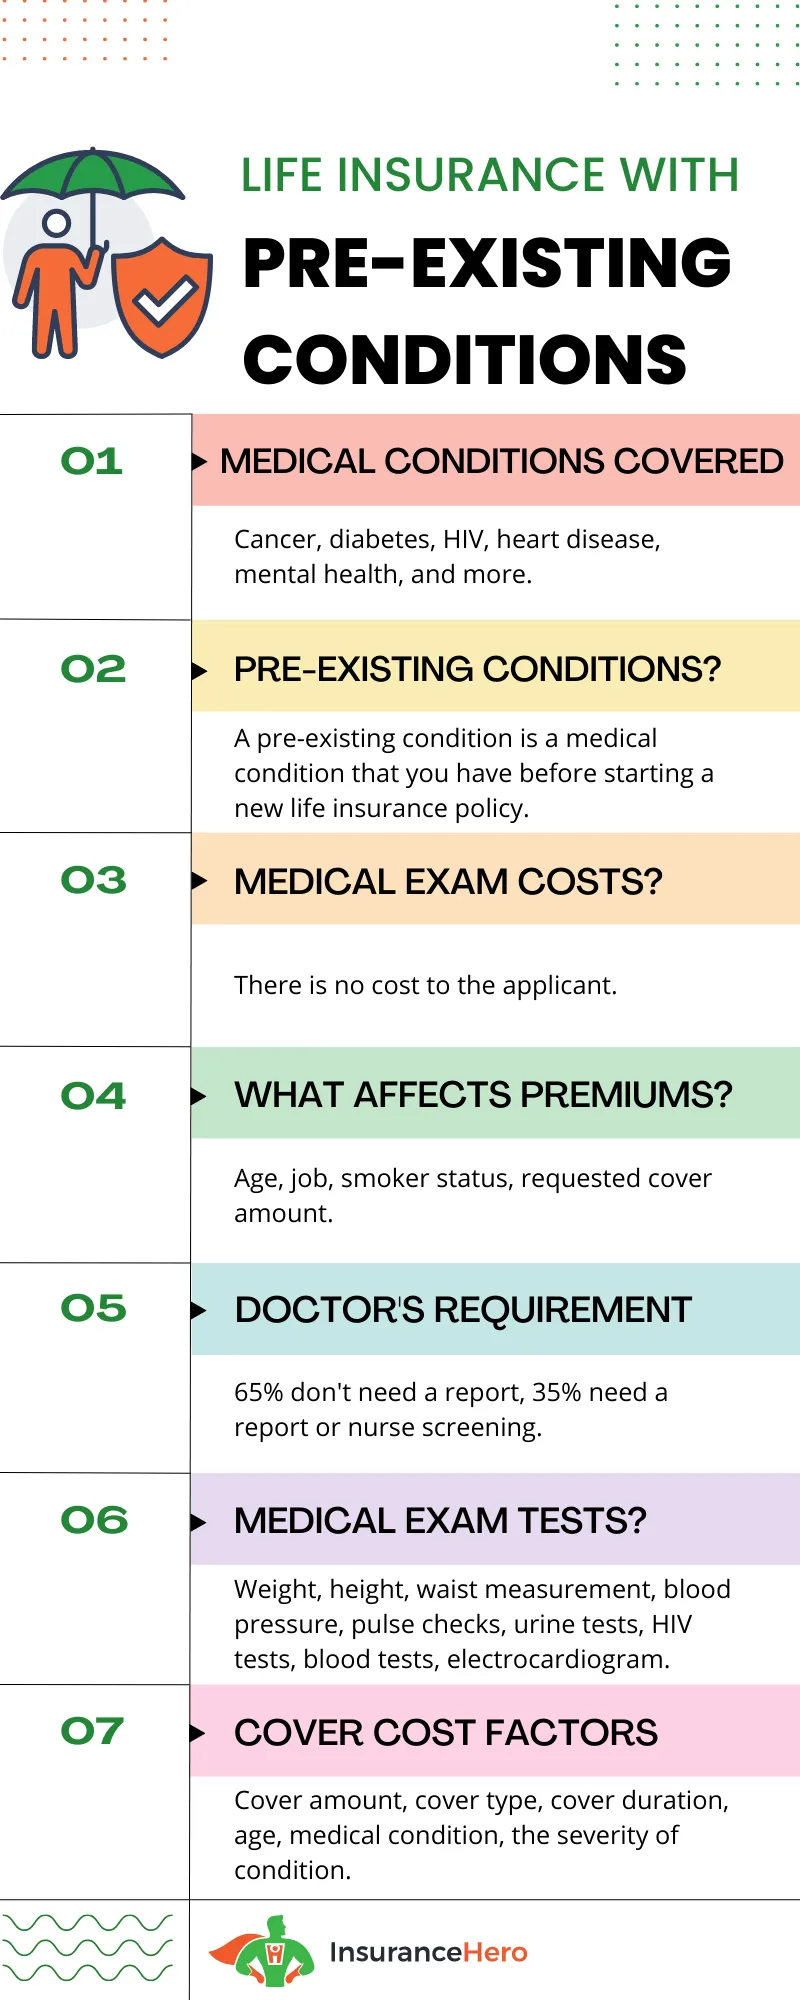
You still have alternatives and that's when impaired threat life insurance coverage comes into the picture. Keep in mind: You can get life insurance protection with a medical condition.
Whether you have medical or non-medical high-risk factors, you still likely have options. The key is to match the policy choices to your goals and existing financial or individual situations.
It is a hassle-free choice for those with crucial health problems looking for guaranteed approval but at a greater premium and lower coverage amount. These policies include a waiting duration of 2 to 3 years for non-accidental deaths before complete advantages apply. Streamlined concern policy type is another no-exam alternative that avoids physical lab tests, but involves evaluation through a health questionnaire and data checks.
The costs are typically lower than guaranteed concern policies however higher than conventional totally underwritten policy types. Term life insurance deals coverage for a set duration of 10-40 years that stays the very same throughout the policy's term. It can be a suitable alternative for those seeking cost effective coverage for short-term requirements and covering significant financial responsibilities.
Specialized Coverage for Post-Treatment Cancer Survivors
Whole life insurance coverage offers lifelong coverage with money worth build-up. It often comes at a greater expense and those with relatively steady health conditions who do not mind going through a medical test might unlock higher protection. Particular versions like final cost insurance coverage may be appropriate for covering smaller coverage requirements. Here's how you can pick: Know the seriousness of your scenario to comprehend the schedule of policy alternatives. Avoid assuming and instead make comparisons across several insurance providers. Not all insurance companies may offer comparable protection choices and guaranteed problem is not your only option. Different insurance providers may assess threat differently, so always compare quotes.
Timing matters, so wait if your condition is enhancing to certify for much better options later on. Even as an impaired-risk candidate, you may still be able to get protection.
Here are some pointers you might follow: Make sure that your condition is well handled and you follow the treatment strategy. Keep your medical records useful to reveal stability in your health. Try quitting risky way of life habits like smoking or alcohol usage. Handle healthy way of life routines for weight management. Prevent applying instantly after a condition is detected.
Download and complete any applicable surveys suggested based off the preliminary questionnaire.
Managing Insurance Needs for Diabetic Applicants
Life insurance can be confusing, specifically when it concerns underwriting. Many individuals struggle to comprehend the procedure and are typically misinformed by typical misconceptions. This article seeks to clarify life insurance coverage underwriting by presenting clear, precise info to help you make notified choices. It has actually typically been stated that underwriting is an extremely elaborate and lengthy procedure.
A lot of business now provide quick underwriting alternatives, which enable you to minimize the time essential to get insured. This suggests you could get protection the fastest method without jeopardizing on thoroughness in its appraisal. Stay ahead of the industry with special feature stories on the top companies, professional insights and the latest news delivered directly to your inbox.
While it's true that health plays a big function in underwriting, insurance providers think about numerous elements, consisting of age, way of life, and household case history. Even if you have some health issues, you can still discover competitive rates customized to your circumstance. It's all about finding the ideal policy that matches your needs and circumstances.
High-Risk Life InsuranceEach policy type, the quantity of protection you want, and the analysis will depend on it. For numerous policies, especially those with lower protection amounts, the procedure can be simple and does not require much time. Some even use no-exam policies, which rely on existing medical records and other data and make determinations based on that.
Insurance companies are eager to offer cover to as many people as possible. To this end, they should ensure that these premiums will be based on the level of the threat. Accurate assessment of one's risk will allow underwriters to offer a policy that safeguards one at a reasonable rate.
Managing Life Insurance for Modern Diabetic Applicants
Medical underwriting is one aspect that might impact what you pay for your life insurance premium. Let's take an appearance at how medical life insurance underwriting can impact your policy.
In the case of health insurance coverage, the healthier you are, the less you'll most likely have to pay for your premium. Medical underwriting is a similar process for life insurance coverage.

1 The insurer takes a look at medical history, way of life practices, demographics, and other elements related to medical needs. After an insurance provider collects medical details, an insurance coverage company will use analytical analysis to identify the applicant's rate class and make a recommendation that best fits their scenario.
Medical underwriting3 is just one part of the entire life insurance coverage underwriting process. Life insurance business often also look at financial status, such as income or bankruptcy history, throughout the life insurance underwriting process. These elements assist an insurer supply the very best rate based upon your distinct monetary circumstance.
Without verification that case history and other aspects including life insurance coverage do not posture a threat, a life insurance business might charge a higher premium to remain protected. Depending upon how high of a threat an insurance company identifies an applicant to be, a premium may be lower or greater than average.
Managing Life Insurance Needs for Diabetic Applicants
In some cases, like when medical underwriting is not a requirement, life insurance underwriting may be finished in as low as 24 hours. In others, the life insurance coverage underwriting process can take a few days to a number of months. The length of the medical underwriting process for life insurance coverage differs. If red flags pop up in an application, an underwriter may take more time to investigate.

Table of Contents
Latest Posts
Integrating Life Insurance with Special Needs Trust Planning

Maximizing Estate Funding with Permanent Life Insurance
The Changing Landscape of Special Needs Planning for Travelers
Latest Posts
Integrating Life Insurance with Special Needs Trust Planning
Maximizing Estate Funding with Permanent Life Insurance
The Changing Landscape of Special Needs Planning for Travelers