All Categories
Featured
Expert Medical Underwriting Best Practices
Evaluating Diabetic Insurance Policies in 2026
Navigating Term Coverage for HIV Applicants

New Policies for HIV Positive Applicants

Steps for a Special Needs Trusts With Insurance
If you're living with HIV, you may have discovered it exceptionally challenging if not difficult to discover life insurance coverage until just recently. The bright side is that with medical advances, HIV is now seen similarly to most other persistent illness by life insurance companies. And as an outcome, we are happy to broaden coverage and deal life insurance for healthy individuals dealing with HIV.As one of the nation's largest insurance provider, Guardian is amongst the first and few in the market to extend this dedication and offer both term life and entire life insurance choices to individuals coping with HIV.
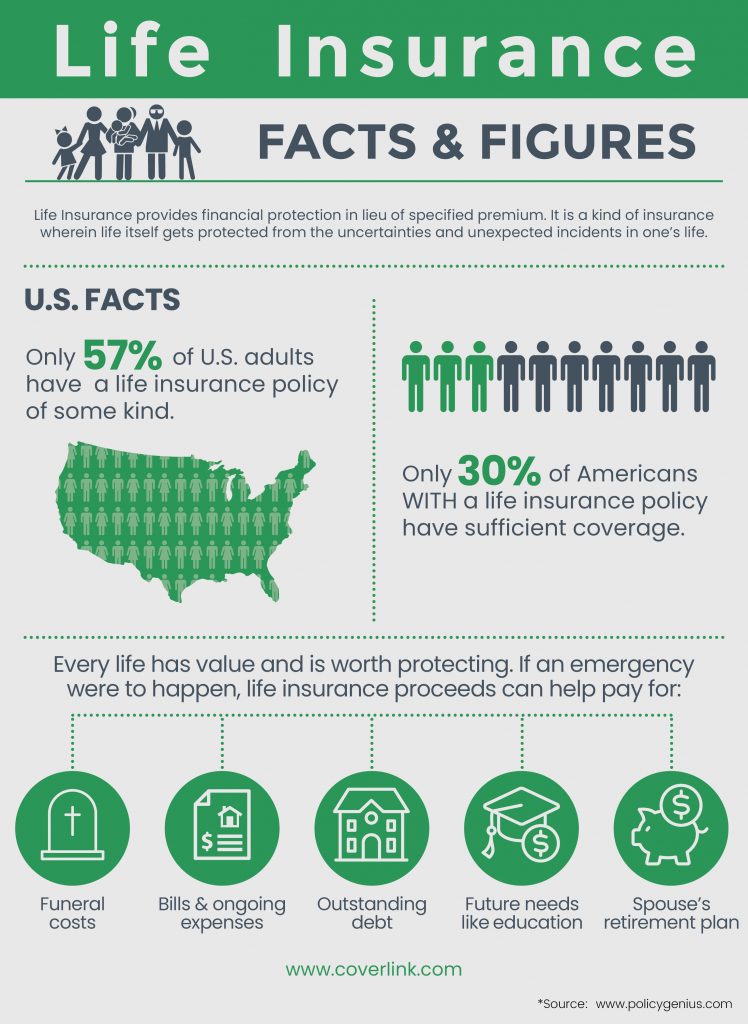
Whether it's entire life or term life, getting life insurance protection is among the fundamental methods to help prepare for life's uncertainties and secure individuals who depend on you for monetary assistance after you pass away. With whole life insurance coverage, you'll have a lifetime of security that's anticipated to help meet your goals for the rest of your life1.
It's yours to utilize as you wish. With cash value development and the capability to provide living benefits, whole life insurance can be a flexible and multifunctional tool in your total monetary portfolio.Term life insurance coverage methods having protection for a specified duration, usually in between 10 and thirty years. During that term, you guarantee to pay a premium monthly and in return, a life insurance business promises to pay a specific survivor benefit to your beneficiaries if you pass away during the term. When the term ends, so does your life insurance coverage security. Unlike entire life insurance coverage, the money value element is not offered with term life policies. Depending on your situation and financial resources, one of these life insurance policy alternatives might appropriate to achieve your goals. Every life insurance coverage applicant need to undergo a medical assessment called underwriting to assist figure out coverage credentials. For HIV positive candidates, additional underwriting requirements should be fulfilled to be considered for a policy. To qualify one need to: Self-identify as a specific living with HIVAre in between ages 20 and 65Have been on highly active antiretroviral therapy for a minimum of two years and demonstrate favorable lab resultsHave not had an AIDS defining condition or illnessNo history of Hepatitis BMust be Hepatitis C Ab unfavorable or curedHIV viral load is undetectableCD4 count should be above 350 and never ever have actually been listed below 200No history of intravenous substance abuse(within the last 7 years)Is under the care of a medical professional concentrating on dealing with HIV clients Expand all Yes, most HIV positive candidates can get life insurance coverage here at Guardian. Contact a Guardian financial professional in your location to learn how to use. Some business offer Guardian group life insurance at work.
High-Risk Life InsuranceAt Guardian, we provide both term life and whole life insurance coverage to individuals living with HIV, who meet the laid out criteria. Yes. For certified HIV positive applicants, Guardian uses a$25,000 minimum and approximately $10,000,000 optimum for entire life insurance. A person dealing with HIV may be considered for a Guardian whole life or term life policy at basic or subpar premiums, depending on each individual's circumstance. YES You would require to reveal your HIV medical diagnosis when requesting a new life insurance policy. Not discussing relevant medical information can cause significant problems when your loved ones require to claim on your policy.'Non-disclosures'are one of the main factors for life insurance not paying, so it is essential to be sincere with your insurance company. Your life insurance policy and prices will be based upon your health at the time you used. Your life insurance business doesn't require to be told about new medical conditions that you are diagnosed with after your policy is active. This would depend upon the result of the HIV test, and a negative test result will not affect your life insurance coverage application. If you are HIV favorable, this can impact the cost of your policy which is why it is very important to speak with the right insurer. Some life insurance companies are more understanding of HIV and are much better matched to applicants who are HIV positive. Insurer aren't permitted to share your HIV status without your authorization, so this isn't something that you need to stress over. If you pass away, your loved ones or selected beneficiaries will be paid a cash lump amount by your insurance provider. This money can use extra financial backing at a tough time and assists your household to pay for essential bills and expenses.
High-Risk Life InsuranceThe 2 main kinds of life insurance are: Level term life insurance coverage: This secures your family and pays a set cash lump amount that you select when you purchase your policy. NO Private medical insurance has actually been designed to cover new, severe medical conditions. As HIV is a chronic( long-term) condition, you won't have the ability to declare to cover the cost of personal HIV treatment. Personal medical insurance can supply support in otherareas and can still be beneficial for individuals dealing with HIV. Health insurance works in a different way from life insurance coverage and being HIV positive shouldn't avoid you from buying a health insurance policy. You will not usually be able to declare for HIV treatment or to treat issues triggered by HIV, however can claim for other short-term medical concerns. Buying when you have a chronic, pre-existing health condition can be tough. Life insurance coverage companies will often charge higher premiums for policyholders who have health problems. Sometimes, they might completely reject you coverage outright. If you're coping with HIV (human immunodeficiency virus), youmay believe that life insurance coverage is out of reach. Let's walk through some of the common obstacles to obtaining life insurance coverage for people with HIV and how to buy protection to meet your needs. After its initial discovery, HIV and AIDS (advanced immunodeficiency syndrome)clients could typically anticipate a typical life expectancy of a year or less. Life insurance companies would deem these people too dangerous to insure and would deny coverage. In these cases, providers will often reject coverage. Due to advances in medicine, treatment for HIV has actually significantly improved. These improved treatments avoid most HIV cases from progressing to AIDS. They likewise permit the majority of the to lead reasonably healthy, average livesalmost. While people dealing with HIV may not have full access to conventional life insurance coverage policies yet, thereare insurer out there who have taken notification of these statistics and loosened their constraints rather. States like California, meanwhile, are presenting legislation to prohibit life insurance coverage business from rejecting protection based on HIV-positive test results. Life insurance coverage takes numerous factors into consideration, including your age, family history, earnings, job threat level andof courseyour medical history. This consists of whether you're dealing with HIV.Many life insurance coverage applications inquire about a potential insurance policy holder's HIV status.

Latest Posts

Expert Medical Underwriting Best Practices

Evaluating Diabetic Insurance Policies in 2026
Navigating Term Coverage for HIV Applicants