All Categories
Featured
How to Secure Impaired Risk Insurance

Expert Medical Underwriting Best Practices

New Policies for HIV Positive Applicants
Table of Contents
Make a danger selection from the list above.
Dual-Eligible Medicare Medi-CalWhat will disqualify me from life insurance coverage is among the most browsed concerns in the life insurance market and the most frequently misconstrued. The facility embedded in the concern that there is a set list of conditions, medications, or circumstances that prevent protection is not how underwriting actually works.
The overwhelming bulk of circumstances that people refer to as "disqualifying" are really rate-impacting, carrier-specific, product-specific, or documentation-dependent meaning the same candidate who gets a decline from one provider might get a standard or modestly rated deal from another, and the same candidate who can not certify for totally underwritten term life might qualify for a long-term design or simplified problem product that serves the very same family security objective at a manageable expense.
Integrating Insurance with Special Needs Trust Planning
The most essential reframe for any applicant researching what will disqualify them from life insurance coverage is this: a decline is one carrier's choice, at one moment, based on one set of underwriting guidelines, applied to one set of facts as that carrier received them. It is not a universal decision.
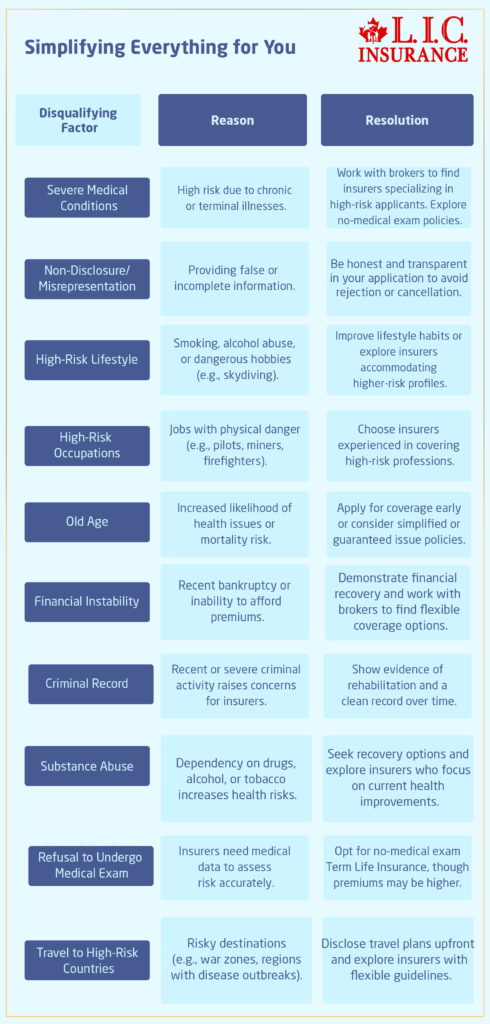
Tell us what's going on health history, medications, develop, occupation, visa status, or a previous decrease and we'll map the very best approval course available for your particular scenario. The most helpful structure for understanding what will disqualify someone from life insurance is a spectrum instead of a list. Different factors sit at different points on this spectrum from real decline sets off that correspond throughout practically all carriers to factors that simply adjust the premium at most of carriers while keeping coverage available.
Element Impact Level Typical Result atStandard Providers Course Forward Active terminal disease/ end-stage organ failure Real disqualifier Decline at essentially all providers for totally underwritten protection Guaranteed problem final expense might be available; graded advantage typically uses Active cancer in treatment True disqualifier throughout treatment Postpone at almost all providers until treatment ends and remission is recorded Apply after remission disease-free periods bring back conventional protection gain access to; strategy the application timing thoroughly Really current major cardiac event (last 312 months) Carrier-specific postponement Postpone pending stability window; most carriers need specified duration post-event Document heart rehabilitation, follow-up care, and EF; reapply after stability duration at cardiac-experienced carriers Uncontrolled diabetes with several issues Severe decline or heavy ranking Decrease or heavy table ranking depending on complication severity and A1C pattern Professional carriers for impaired risk; simplified concern as interim; enhance control and reapply Well-controlled chronic condition (diabetes, hypertension, COPD) Rate-impacting not disqualifying Standard to table-rated at most providers; preferred possible at favorable providers Provider matching to the most favorable underwriting approach for the particular condition Stable psychological health history (depression/anxiety, treated) Rate-impacting to minimal Frequently standard to a little ranked; long-lasting stability substantially improves outcome File stability, treatment consistency, and absence of hospitalizations; carrier choice matters Prescription mismatch with application disclosure Process-driven preventable Delay, additional questions, prospective decrease or score if provider interprets as misrepresentation Accurate full disclosure before application; context offered in broker letter; prescreen to recognize provider most likely to view profile properly Raised BMI/ develop otherwise healthy Rate-impacting at most carriers Table ranking or construct decrease at stringent providers; standard possible at carriers with more beneficial construct guidelines Provider selection particularly for construct standards; beneficial labs can offset build concern at some providers High-risk occupation or avocation Carrier-specific rate or exclusion Flat additional additional charge or activity exclusion rider; outright decline at some carriers Specialized carriers for particular occupation/avocation profiles; exclusion riders may attain protection without activity-related additional charge Visa/ residency/ paperwork gaps Carrier-specific Decrease at providers without visa underwriting; approval at providers with clear visa documentation frameworks Target providers with established H1B, TN, or other visa underwriting structures; documents list is the crucial variable The table reveals the central insight: what will disqualify somebody from life insurance at one carrier is typically manageable at a different provider, with different documentation, or through a various item for the bulk of situations.
Specialized Coverage for Post-Treatment Cancer Survivors
Everything else exists on a spectrum where carrier matching, product choice, documents quality, and application timing produce meaningfully different outcomes. Our resource on am I too young for life insurance covers the age measurement of eligibility concerns, which matters context for understanding why timing both of application and of life stage impacts outcomes throughout many classifications in this table.
The underwriting procedure is not a challenge course designed to eliminate as numerous candidates as possible it is a danger prices system developed to determine whether a carrier can make a long-term promise (paying a survivor benefit when the insured dies) at a premium that shows the actual actuarial danger of that guarantee becoming due earlier than anticipated.

Latest Posts

How to Secure Impaired Risk Insurance
Planning for a Special Needs Trust With Insurance
Insurance Options for Chronic Kidney Disease and Dialysis Patients