All Categories
Featured
How to Secure Impaired Risk Insurance

Expert Medical Underwriting Best Practices

Evaluating Diabetic Insurance Policies in 2026
Table of Contents

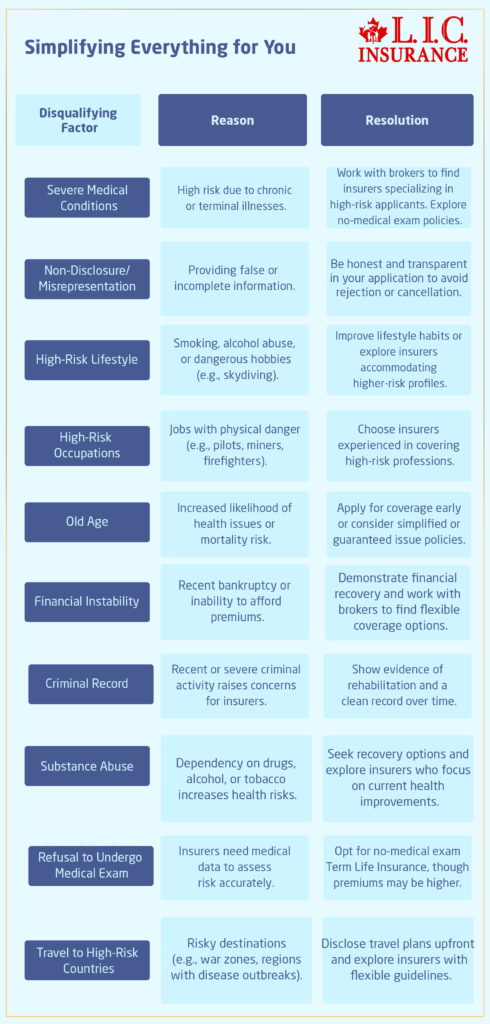
Life insurance coverage can supply essential financial security for enjoyed ones, but those with preexisting conditions frequently have a harder time getting a life insurance policy. Still, many medical conditions, consisting of diabetes, do not automatically disqualify a person for insurance coverage. For the most part, people with diabetes can still get life insurance; they might need to pay more than an individual without a preexisting condition.
In this post, we'll help explain: Insurance suppliers base premiums on the applicant's anticipated durability. Preexisting medical conditions can shorten life span, which is why life insurance coverage for some diabetics tends to be costlier than it is for people without any pre-existing conditions. Even when blood sugar level is well controlled, the illness can potentially cause problems, so it is a danger element.
These consist of, but aren't limited to: ObesityHeart diseaseHigh high blood pressure (high blood pressure)HypertensionStrokeIssues with eyes, teeth, and other organsKidney disease or failureNeuropathyLimb amputationHowever, not all diabetics are the same. Life insurance business rate applicant danger based on several factors, including case history, family case history, existing health, age, and way of life (such as tobacco usage).
Candidates with well-managed diabetes and no problems might get approved for more favorable policy terms. The life insurance coverage company will typically have you finish a medical underwriting process to identify your risk to insure. This can consist of a questionnaire that inquires about your diabetes, in addition to the basic medical concerns on the life insurance application.
Goldencare vs Harmony SoCalInsulin treatment, which is frequently needed for Type 1 diabetes and in some cases for Type 2 diabetes, might affect life insurance premiums. The insurance coverage company might also need medical records to confirm your health history. In addition, you will frequently need to finish a physical exam (specifically if you're looking for a high protection amount), and the life insurance business might also need a microalbumin test, which can help spot early signs of kidney damage.
Advanced Specialized Insurance Protection Strategies
complete underwriting policies" below.) As part of the underwriting process, the life insurance coverage business will likewise ask about the type of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. People with each kind of diabetes can still get life insurance coverage, however depending on the base diagnosis, the application process may be more troublesome, and the protection offerings more minimal.
Goldencare vs Harmony SoCalWhen it happens later in life, that suggests it has affected your body and health for a much shorter length of time. Type 1 diabetes is often identified in kids or teenagers, making it a greater danger, and for that factor, it is usually associated with higher premiums. Type 2 diabetes is typically detected at a later age than Type 1, so it has less time to impact the body.
If that holds true, and you've learned how to keep it under control with diet and exercise, you will likely receive the most cost effective rates (in relation to others with diabetes). Even with Type 2 diabetes, individuals with diabetes-related issues and those who are insulin-dependent will find their life insurance choices more minimal and their premium expenses higher due to greater danger.

In many circumstances, gestational diabetes disappears after offering birth, however not constantly. In any case, pregnant women with gestational diabetes might wish to wait a number of months after delivering before requesting life insurance. Presuming the diabetes goes away, it will then be much easier and less costly to get a life insurance policy.
Lots of term policies can convert to irreversible life insurance coverage before the term expires without requiring extra medical underwriting. If available, conversion can be an option to consider for people who bought a term life insurance policy before they were detected with diabetes and wish to extend their coverage. Permanent policies, such as whole life insurance coverage or universal life insurance, are usually more pricey, but they are designed to cover you for life.
Top Advantages of Specialized Impaired Life Insurance
2,3 It may be best to buy as much life insurance coverage as you'll need (and can manage) as quickly as possible, instead of wait to include more in the future. This is because life insurance coverage ends up being more pricey the older you get, and a hidden condition like diabetes will usually raise the expense further.

Latest Posts

How to Secure Impaired Risk Insurance
Planning for a Special Needs Trust With Insurance
Insurance Options for Chronic Kidney Disease and Dialysis Patients